Dog Insurance and Pet Care Costs Explained
Dog Insurance & Costs By James C. • January 29, 2026
Owning a dog in Australia is rewarding, but it is not cheap. Between food, vet visits, grooming, and insurance, the average dog owner can spend over $3,000 a year on proper care alone. That number surprises many people!
Some costs are obvious. Others hit when you least expect them. Emergency vet bills. Ongoing health issues. Premiums that rise as your dog ages. It adds up quickly, and poor planning can turn stress into tough decisions.
This guide breaks it all down. You will see the real costs of dog ownership, how dog insurance works, what is worth paying for, and how to budget smarter so your dog gets the care they deserve.
The True Cost of Owning a Dog in Australia
Owning a dog in Australia comes with more financial responsibility than many people expect. Beyond the initial excitement, there are ongoing costs that continue for the entire life of your dog. On average, dog owners can expect to spend between $2,500 and $4,000 per year, depending on breed size, health, and lifestyle.
Food is one of the biggest recurring expenses, especially for medium to large breeds of dogs on premium diets. Routine veterinary care also adds up, including vaccinations, parasite prevention, dental checks, and annual health exams. Even healthy dogs need regular visits to stay that way, which is why owners should understand how often dogs should see a vet.
Then there are the costs that many owners underestimate. Grooming, training, replacement toys, bedding, and other items on a new puppy supplies checklist all contribute over time. Emergency vet visits can quickly reach thousands of dollars, particularly if surgery or ongoing treatment is required. As dogs age, medical expenses often increase.
Understanding the true cost upfront helps owners plan realistically, avoid financial stress, and ensure their dog receives consistent, high-quality care throughout every stage of life.
Common Dog Care Expenses Every Owner Should Budget For
Here are the everyday dog care costs most owners underestimate, yet will face year after year once a dog becomes part of the family.
1. Routine Veterinary Care and Preventative Treatments
Annual vet check-ups, vaccinations, worming, flea control, and parasite prevention are non-negotiable costs. Even with a healthy dog, these expenses add up across the year.
Expect regular visits to maintain immunity, monitor weight and dental health, and catch issues early. Skipping preventative care often leads to higher costs later, especially when minor health concerns escalate into expensive treatments or emergencies.
2. Food, Treats, and Ongoing Nutrition
Quality nutrition is a monthly expense that varies by breed size, age, and dietary needs. Puppies, large breeds, and dogs with sensitivities often cost more to feed.
On top of main meals, treats, supplements, and chews become part of everyday care. Choosing cheaper food may reduce short-term spending, but can increase vet bills over time due to poor nutrition-related health issues.
3. Grooming, Hygiene, and Coat Maintenance
Some dogs need professional grooming every six to eight weeks, while others require regular home maintenance. Costs include grooming appointments, shampoos, brushes, nail trims, and ear cleaning products.
Breeds with long or curly coats generally cost more to maintain. Proper grooming is not cosmetic only. Following practical dog grooming and hygiene tips helps prevent skin infections, matting, and discomfort that can lead to costly vet visits.
4. Training, Enrichment, and Behaviour Support
Training classes, toys, mental stimulation tools, and behavioural support are often overlooked expenses. Puppy school, obedience training, or one-on-one sessions help prevent destructive habits and anxiety-related behaviours.
Enrichment toys and activities keep dogs mentally balanced and reduce boredom. Investing in training early often saves money later by preventing damage, stress, and common puppy behaviour problems that are harder to fix.
Unexpected Dog Expenses Most Owners Forget
Unexpected costs can catch even experienced dog owners off guard. These are the dog expenses many people forget to budget for until they arrive without warning.
- Emergency Veterinary Visits: Accidents, sudden illness, or ingestion of harmful objects can lead to urgent vet care. After-hours clinics, diagnostics, and surgery often cost thousands, creating financial stress without preparation.
- Ongoing Treatment for Chronic Conditions: Allergies, arthritis, digestive issues, or skin conditions may require lifelong medication, special diets, and repeat vet visits, increasing monthly costs well beyond routine care.
- Boarding, Pet Sitting, and Travel Care: Holidays, work travel, or emergencies often require boarding or in-home pet sitters. Quality care is not cheap, especially during peak holiday periods.
- Replacement and Damage Costs: Chewed furniture, destroyed bedding, fencing repairs, or repeated replacement of toys and leads can quietly add up, particularly during puppy and adolescent stages.
Understanding Vet Bills and Routine Pet Care Costs
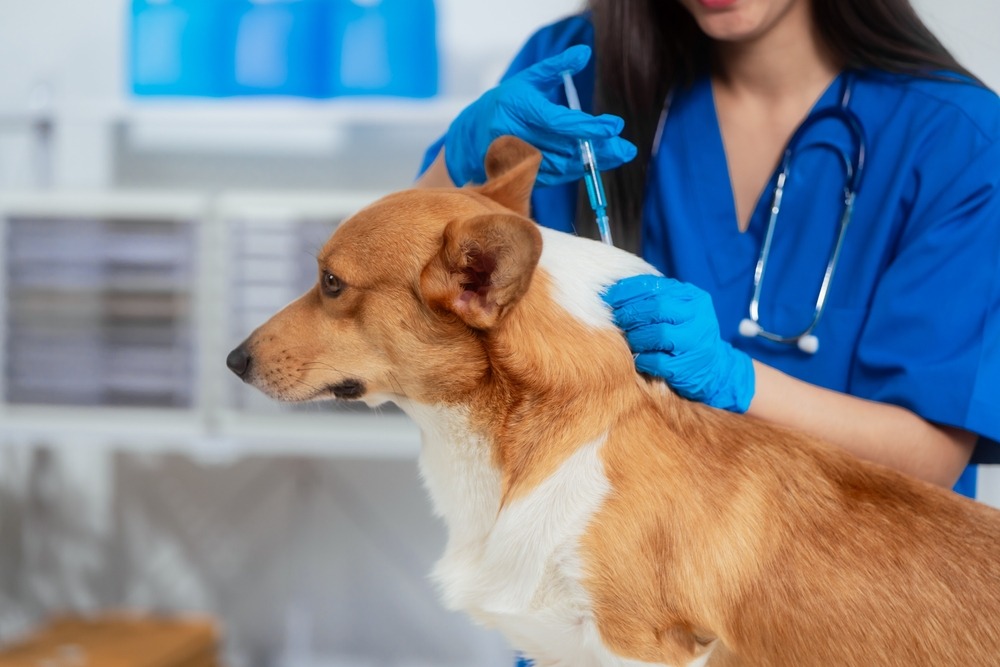
Veterinary care is one of the most important and ongoing costs of dog ownership in Australia. Routine vet expenses begin with a puppy vaccination schedule, health checks, and parasite prevention, all of which are essential for keeping dogs healthy and preventing serious illness.
Annual check-ups often include physical exams, dental assessments, and early detection of underlying conditions.
Beyond routine care, vet bills can rise quickly when diagnostic tests are needed. Blood work, X-rays, ultrasounds, and specialist consultations are common and can significantly increase costs. Dental procedures are another frequent expense, especially as dogs age, and may require anaesthesia.
Emergency veterinary care is where many owners feel the financial pressure. After-hours visits, surgeries, and hospital stays can cost thousands of dollars, often without warning. As dogs get older, the likelihood of ongoing treatment increases, with arthritis management, prescription diets, and long-term medication becoming more common.
Understanding these costs helps owners budget realistically and make informed decisions about insurance, preventative care, and long-term planning for their dog’s health.
What Is Dog Insurance and How Does It Work?
Dog insurance is designed to help cover the cost of unexpected veterinary bills, reducing the financial stress that can come with accidents or illness. In Australia, dog insurance works by reimbursing a portion of eligible vet expenses after you pay the bill upfront. You then submit a claim to your insurer for assessment.
Most policies allow you to choose your level of cover, including benefit limits, excess amounts, and reimbursement percentages. These choices directly affect your monthly premium. Higher coverage generally means higher premiums, but lower out-of-pocket costs when something goes wrong.
Dog insurance typically falls into different categories, such as accident-only cover or more comprehensive accident and illness policies. Some plans may also offer optional extras, although routine care is usually excluded.
Waiting periods apply when a policy starts, meaning certain conditions are not covered immediately. Pre-existing conditions are also excluded. Understanding how dog insurance works helps owners choose appropriate cover and avoid surprises when making claims.
Types of Dog Insurance Policies in Australia
These are the main dog insurance options available in Australia, each designed to suit different budgets, lifestyles, and levels of risk.
1. Accident-Only Dog Insurance
This is the most basic and affordable type of cover. Accident-only policies help pay for injuries caused by events like falls, car accidents, or bites. They do not cover illnesses, ongoing conditions, or routine care.
This option suits owners wanting emergency financial support without committing to higher premiums, but it offers limited protection if your dog develops health issues over time.
2. Accident and Illness Dog Insurance
This is the most common choice for Australian dog owners. It covers injuries and a wide range of illnesses, including infections, digestive issues, and chronic conditions that develop after the policy starts.
Premiums are higher than accident-only cover, but it provides broader peace of mind. Routine care is usually excluded unless optional extras are added to the policy.
3. Comprehensive Dog Insurance
Comprehensive policies offer the highest level of protection. They include accident and illness cover plus selected extras such as dental treatment, behavioural therapy, and specialist care.
These policies often have higher annual benefit limits and fewer exclusions. While premiums are higher, comprehensive cover suits owners who want maximum financial protection and minimal surprises when vet bills arise.
4. Wellness and Routine Care Add-Ons
These optional add-ons are designed to help with everyday pet care costs. They may cover vaccinations, the right time to desex your dog, flea and worming treatments, and annual check-ups.
Wellness add-ons increase monthly premiums but can offset routine expenses. They are best for owners who prefer predictable budgeting and want some return on regular preventative care spending.
What Dog Insurance Typically Covers
Dog insurance is designed to protect owners from large, unexpected veterinary bills. Here is what dog insurance policies in Australia typically include.
1. Veterinary Consultations and Diagnostic Testing
Most dog insurance policies cover vet consultations related to accidents or illness. This includes diagnostic tests such as blood work, X-rays, ultrasounds, and scans. These tests are often required to reach an accurate diagnosis and can quickly increase costs without insurance support.
2. Surgery, Hospitalisation, and Anaesthesia
Surgical procedures resulting from accidents or medical conditions are usually covered. This includes hospital stays, operating theatre fees, anaesthesia, and post-operative monitoring. These are among the most expensive veterinary services, making this coverage one of the most valuable aspects of dog insurance.
3. Prescription Medications and Ongoing Treatment
Insurance commonly covers prescription medications needed to treat eligible conditions. This may include antibiotics, pain relief, or long-term medication for chronic illness. Ongoing treatment plans linked to covered conditions can also be included, subject to policy limits.
4. Specialist Care and Rehabilitation Services
Many policies include referrals to veterinary specialists, such as surgeons or dermatologists. Some also cover rehabilitation therapies like physiotherapy or hydrotherapy. Coverage limits apply, but these services support recovery and long-term mobility for injured or recovering dogs.
What Dog Insurance Usually Does NOT Cover
These are the common exclusions that catch many dog owners off guard, making it important to read policy details before signing up.
- Pre-Existing Conditions: Any illness or injury your dog showed signs of before the policy started is usually excluded, even if symptoms return later or worsen over time.
- Routine and Preventative Care: Vaccinations, annual check-ups, flea and worming treatments, nail trimming, and desexing are typically not covered unless a wellness add-on is included.
- Elective and Cosmetic Procedures: Procedures such as tail docking, ear cropping, or non-essential surgeries are excluded, as they are not considered medically necessary treatments.
- Breeding and Pregnancy Costs: Mating, pregnancy care, whelping complications, and related veterinary services are generally excluded from dog insurance policies.
- Behavioural and Training Costs: Basic training, obedience classes, and behaviour correction are usually not covered unless the policy includes limited behavioural therapy under strict conditions.
How Much Does Dog Insurance Cost in Australia?
Dog insurance costs in Australia vary widely based on your dog’s breed, age, health, location, and the level of cover you choose. On average, most owners pay between $40 and $90 per month, though premiums can be lower for young, mixed-breed dogs or higher for larger breeds and older dogs with increased risk of illness.
Policy options also influence price. Basic accident-only cover is usually the most affordable, while comprehensive cover that protects against both accidents and illnesses costs more. Choosing higher benefit limits and lower excesses increases monthly premiums, but reduces out-of-pocket costs when you make a claim.
Age is another big factor. Puppies and young dogs typically attract lower premiums, but as your dog gets older, premiums rise because older dogs are more likely to develop health issues that require treatment.
Understanding these cost drivers helps you compare policies and choose a level of cover that aligns with your budget and your dog’s needs.
Factors Influencing Cost
Several factors shape how much you will pay for dog insurance in Australia. Understanding them makes comparing policies far easier and more accurate.
1. Your Dog’s Breed and Size
Breed plays a major role in insurance pricing. Some breeds are more prone to inherited health conditions, joint issues, or respiratory problems, which increases claim risk.
Larger dogs also tend to cost more to treat due to medication dosage, imaging, and surgery costs. As a result, insurers price premiums higher for breeds and sizes associated with increased veterinary expenses.
2. Age and Health History
Younger dogs usually attract lower premiums because they are less likely to need ongoing treatment. As dogs age, insurance costs rise due to higher illness risk.
Any previous injuries or medical history can also influence pricing. While pre-existing conditions are excluded, insurers still assess age-related risk when setting premiums and policy limits.
3. Level of Cover and Policy Features
The type of policy you choose directly impacts cost. Accident-only cover is cheaper, while accident and illness or comprehensive cover costs more.
Higher annual benefit limits, lower excess amounts, and higher reimbursement percentages increase premiums. Optional extras, where available, also raise monthly costs and should be assessed carefully.
4. Location and Veterinary Costs
Where you live matters. Veterinary services in major cities often cost more than in regional areas, and insurers factor this into pricing.
Suburbs with higher average vet fees usually see higher premiums. Access to specialist clinics and emergency hospitals in your area can also influence insurance costs.
Is Dog Insurance Worth It?
Deciding whether dog insurance is worth it depends on your dog, your finances, and how comfortable you are managing unexpected veterinary costs.
1. Protection Against Large, Unexpected Vet Bills
Dog insurance helps cover the high cost of emergencies such as surgery, serious illness, or accidents. Vet bills can quickly reach thousands of dollars, and insurance provides financial breathing room so decisions are based on care needs, not immediate cost pressure.
2. Peace of Mind for Long-Term Dog Ownership
Knowing you have coverage reduces stress throughout your dog’s life. As dogs age, health risks increase. Insurance helps owners plan confidently, rather than worrying about future medical expenses or delaying treatment due to cost concerns.
3. When Dog Insurance Makes Financial Sense
Insurance is often worthwhile for large breeds, active dogs, or breeds prone to health conditions. Owners without a dedicated emergency savings fund benefit most, as insurance spreads risk over manageable monthly payments.
4. When Self-Funding May Be an Alternative
For low-risk dogs and owners with strong savings discipline, self-funding vet costs can work. This approach requires consistent saving and readiness to cover large bills without financial strain.
Alternatives to Dog Insurance
Dog insurance is not the only way to manage pet care costs. Some owners prefer alternative approaches depending on their dog’s risk level and financial situation.
1. Self-Funding Through a Dedicated Pet Savings Account
Instead of paying monthly premiums, some owners set aside money in a dedicated savings account for vet care. This approach offers full control over funds and avoids exclusions. However, it requires discipline and may fall short during expensive emergencies early in your dog’s life.
2. Vet Payment Plans and Membership Programs
Some veterinary clinics offer payment plans or wellness memberships that spread routine care costs over time. These can help manage everyday expenses but rarely cover emergencies or specialist treatments, meaning large bills can still arise unexpectedly.
3. Emergency Credit and Buy-Now-Pay-Later Options
Credit cards or payment services may cover urgent vet bills when needed. While convenient, interest and fees can add long-term financial pressure, making this a riskier alternative without careful repayment planning.
4. Combining Savings With Limited Insurance Cover
A hybrid approach can work for some owners. Basic accident-only insurance paired with personal savings offers partial protection while keeping premiums lower. This balances emergency coverage with financial flexibility.
How to Choose the Right Dog Insurance Policy
Choosing dog insurance is not about finding the cheapest option, but the one that protects your dog and your budget long term. See below:
1. Match the Policy to Your Dog’s Breed and Age
Different breeds come with different health risks, which directly affect insurance value. Large breeds and flat-faced dogs often face higher vet costs, while older dogs usually have more exclusions.
Puppies benefit most from early cover before conditions develop. Always consider your dog’s likely health needs over time, not just their current age or condition.
2. Compare Benefit Limits, Excess, and Reimbursement Rates
Look beyond monthly premiums and check annual benefit caps, claim limits per condition, and reimbursement percentages.
A cheaper policy may leave you paying more during a claim. Balancing excess levels with reimbursement rates helps reduce out-of-pocket costs when expensive treatments arise, making the policy genuinely useful in emergencies.
3. Understand Waiting Periods and Exclusions Clearly
Waiting periods apply before you can claim for illnesses, injuries, or specific conditions. Some policies have longer waits for cruciate injuries or dental issues.
Reading exclusions carefully prevents disappointment later. Knowing exactly when cover starts and what is excluded ensures there are no surprises when you need to lodge a claim.
4. Check Claims Process and Customer Support Quality
A policy is only helpful if claims are easy and timely. Look for insurers with straightforward online claims, fast processing times, and responsive support.
Reading customer reviews helps reveal real experiences. A smooth claims process matters most during stressful situations when quick reimbursement can ease financial pressure and allow focus on your dog’s recovery.
5. Choose a Policy That Fits Your Budget Long Term
Insurance is a long-term commitment. Select a policy you can comfortably afford as premiums increase with age. A sustainable policy reduces the risk of cancelling cover when your dog needs it most.
Pet Care Costs Over a Dog’s Lifetime
Here’s how pet care costs and insurance needs change as dogs grow from playful puppies into ageing seniors, helping owners budget smarter at every life stage.
| Cost Category | Puppies | Adult Dogs | Senior Dogs |
|---|---|---|---|
| Insurance Premiums | Lower monthly premiums with broader cover and minimal exclusions when insured early. | Premiums increase gradually with age and risk, but cover remains stable if insured earlier. | Highest premiums, with stricter limits and exclusions. New policies may have reduced coverage options. |
| Veterinary Care | High upfront costs for vaccinations, desexing, microchipping, and frequent early check-ups. | Predictable routine care including annual health checks, dental care, and parasite prevention. | Increased vet visits for monitoring age-related conditions, diagnostics, and ongoing treatment. |
| Training and Behaviour | Puppy preschool, obedience training, and socialisation classes are common early expenses. | Fewer training costs, though behavioural refreshers or lifestyle training may still be needed. | Minimal training costs, but support may be required for mobility or cognitive changes. |
| Food and Nutrition | Puppy-specific diets supporting growth and development, often adjusted frequently. | Stable diets based on size and activity, with occasional dietary changes. | Senior diets or prescription food for joint, weight, or medical management often increase costs. |
| Unexpected Costs | Accidents, foreign object ingestion, and minor injuries during exploration stages are common. | Sudden illness or injury may occur but less frequently with good preventative care. | Chronic conditions such as arthritis, dental disease, and long-term medication become more common. |
Reducing Pet Care Costs Without Compromising Welfare
Managing pet care costs does not mean cutting corners. With smart planning, owners can reduce expenses while still providing high-quality care and a good quality of life.
1. Prioritise Preventive Care and Early Intervention
Preventive care saves money long term. Regular health checks, parasite prevention, dental care, and maintaining a healthy weight reduce the risk of serious illness. Catching issues early often avoids expensive treatments later, lowers emergency vet visits, and keeps your dog healthier across every life stage.
2. Choose Nutrition Based on Value, Not Hype
Expensive does not always mean better. Focus on nutritionally balanced food suited to your dog’s size, age, and activity level. Buying in bulk, avoiding unnecessary supplements, and sticking to consistent diets can reduce waste and vet issues linked to poor nutrition.
3. Use Training and Enrichment to Prevent Costly Problems
Behavioural issues often lead to property damage, injuries, or professional intervention. Investing in early training, enrichment toys, and mental stimulation reduces destructive behaviour and stress-related health problems, saving money over time.
4. Plan for Known and Predictable Expenses
Budgeting for grooming, routine vet visits, boarding, and replacement items spreads costs evenly across the year. Planning avoids financial pressure and ensures your dog never misses essential care due to short-term budget strain.
When to See a Vet Immediately vs Monitor at Home
Knowing when to rush to the vet and when to monitor your dog at home can make a critical difference to their health. Immediate veterinary attention is needed if your dog collapses, struggles to breathe, has uncontrolled bleeding, experiences seizures, shows severe pain, or has repeated vomiting in dogs.
Trauma from accidents, suspected poisoning, or sudden paralysis should always be treated as emergencies.
Some symptoms can be monitored at home for a short period. Mild lethargy, a single episode of vomiting, minor limping, or a temporary loss of appetite may resolve with rest and observation. During this time, keep your dog comfortable, hydrated, and away from strenuous activity.
If symptoms persist beyond twenty-four hours, worsen, or are accompanied by behavioural changes, it is best to seek veterinary advice. Subtle signs like weight loss, recurring itching, or reduced mobility often indicate developing issues. Early intervention reduces long-term health risks and prevents small problems from becoming expensive emergencies.
Common Mistakes Owners Make With Pet Insurance
Pet insurance can be a valuable safety net, but many owners make avoidable mistakes that limit its usefulness. These are the most common issues that lead to frustration and unexpected costs.
1. Waiting Too Long to Take Out Insurance
Many owners delay insurance until problems appear. By then, premiums are higher, and any existing symptoms become pre-existing conditions, permanently excluded. Early cover usually means broader protection, lower costs, and fewer claim restrictions as your dog ages.
2. Not Reading Policy Exclusions Carefully
Policy wording matters. Skipping exclusions can lead to rejected claims for specific conditions, treatments, or breed-related issues. Understanding exclusions upfront helps set realistic expectations and prevents unpleasant surprises during emergencies or ongoing treatment claims.
3. Choosing the Cheapest Policy Without Comparing Coverage
Low premiums often hide low benefit limits, high excesses, or reduced reimbursements. Cheap policies may fail to cover major surgeries or long-term care, leaving owners exposed when serious or expensive veterinary treatment is required.
4. Overlooking Excess, Caps, and Reimbursement Rates
Some owners focus only on the monthly cost and ignore excess amounts, annual caps, and reimbursement percentages. These factors directly affect how much money you actually receive back after a claim is approved.
5. Assuming Routine Care Is Included
Vaccinations, parasite prevention, dental care, and health checks are usually excluded from standard policies. Without separate budgeting for routine care, owners may feel misled even though the policy is working as intended.
Plan Smarter. Care Better.
Dog ownership is a long-term commitment, not just emotionally, but financially too. From everyday essentials to unexpected vet bills, understanding the true costs helps you make calmer, more confident decisions. When you know what to expect, you can focus less on stress and more on enjoying life with your dog.
Dog insurance can be a safety net, but it is not one-size-fits-all. The right choice depends on your dog’s age, breed, lifestyle, and your budget. Planning always beats reacting later.
Ready to start on the right foot? PUPS4SALE helps you find the right dog, connect with trusted sellers, and plan responsibly from day one. Smart choices today lead to happier years together.
FAQs: Dog Insurance and Pet Care Costs in Australia
1. How much does it cost to own a dog in Australia each year?
On average, Australian dog owners spend between $2,500 and $4,000 per year, depending on dog size, health needs, diet, and lifestyle. Larger breeds and dogs with ongoing health conditions usually sit at the higher end of this range.
2. How much is dog insurance per month in Australia?
Dog insurance typically costs $40 to $90 per month. Premiums vary based on breed, age, location, coverage type, excess levels, and benefit limits. Puppies and mixed breeds are often cheaper to insure.
3. Is dog insurance mandatory in Australia?
No, dog insurance is not legally required in Australia. Many owners still choose it to manage the risk of unexpected vet bills that can quickly reach thousands of dollars.
4. What does dog insurance usually not cover?
Most policies exclude pre-existing conditions, routine care, vaccinations, desexing, and elective procedures. Some breeds may also have condition-specific exclusions, making policy review essential.
5. Can I insure an older dog?
Yes, many insurers cover senior dogs, although premiums are higher and coverage may be limited. Early insurance usually offers better long-term value.
6. Is dog insurance worth it, or should I self-fund vet costs?
Insurance suits owners who want financial protection from large, unexpected expenses. Self-funding can work if you maintain a strong emergency savings buffer and have a low-risk dog.
 Add us as a preferred source